Liability insurance can help protect a business from certain claims, but different policies are designed for different risks. Two common types are general liability insurance and professional liability insurance.
General liability generally addresses certain claims involving bodily injury, property damage, and personal or advertising injury. Professional liability generally addresses certain claims arising from professional services, advice, errors, or omissions.
For Colorado businesses, including those in the Colorado Springs area, understanding this distinction can help owners identify gaps and make more informed coverage decisions.
What Is General Liability Insurance?
General liability insurance is designed to address certain third-party claims that can arise during everyday business operations.
For example, a customer could slip and become injured at your business. Your business could also accidentally damage a customer’s property while completing a job. Depending on the circumstances and policy terms, general liability insurance may help address a covered claim and certain associated legal expenses.
General liability coverage may apply to claims involving:
- Bodily injury to a customer or another third party
- Damage to someone else’s property
- Certain personal injuries, such as libel or slander
- Certain advertising injuries
- Legal defense expenses associated with covered claims
General liability does not cover every risk a business may face. Coverage depends on the policy’s limits, exclusions, endorsements, deductibles, and other terms.
What Is Professional Liability Insurance?
Professional liability insurance focuses on claims connected to the professional services, advice, or specialized work a business provides.
This coverage is also commonly called errors and omissions insurance, or E&O insurance. Depending on the profession and policy, it may help address claims alleging that an error, omission, negligent act, or failure to perform a professional service caused a client financial harm.
For example:
- A consultant provides advice that a client alleges resulted in a financial loss.
- A designer overlooks a project requirement, causing delays or additional expenses.
- A technology professional makes an alleged error while implementing a client’s system.
- A service provider fails to complete work according to a contractual standard.
Whether a particular allegation is covered depends on the wording of the policy and the circumstances surrounding the claim.
Professional liability may be relevant for consultants, accountants, designers, technology professionals, real estate professionals, and other businesses that provide advice or specialized services. Coverage varies by profession, carrier, limits, exclusions, and policy terms.
General Liability vs. Professional Liability
| General liability | Professional liability |
|---|---|
| Generally focuses on bodily injury, property damage, and certain personal or advertising injuries | Generally focuses on claims arising from professional services |
| May address accidents at a business or customer location | May address alleged errors, omissions, negligence, or failure to perform |
| Common across many types of businesses | Often relevant to service-based and professional businesses |
| Primarily addresses certain physical and third-party risks | Primarily addresses certain financial losses connected to professional work |
These policies are not necessarily alternatives. A business may face both physical risks and professional-service risks, making both types of coverage appropriate.
Why General Liability May Not Cover a Professional Error
A general liability policy should not automatically be expected to cover a claim arising from professional advice or services.
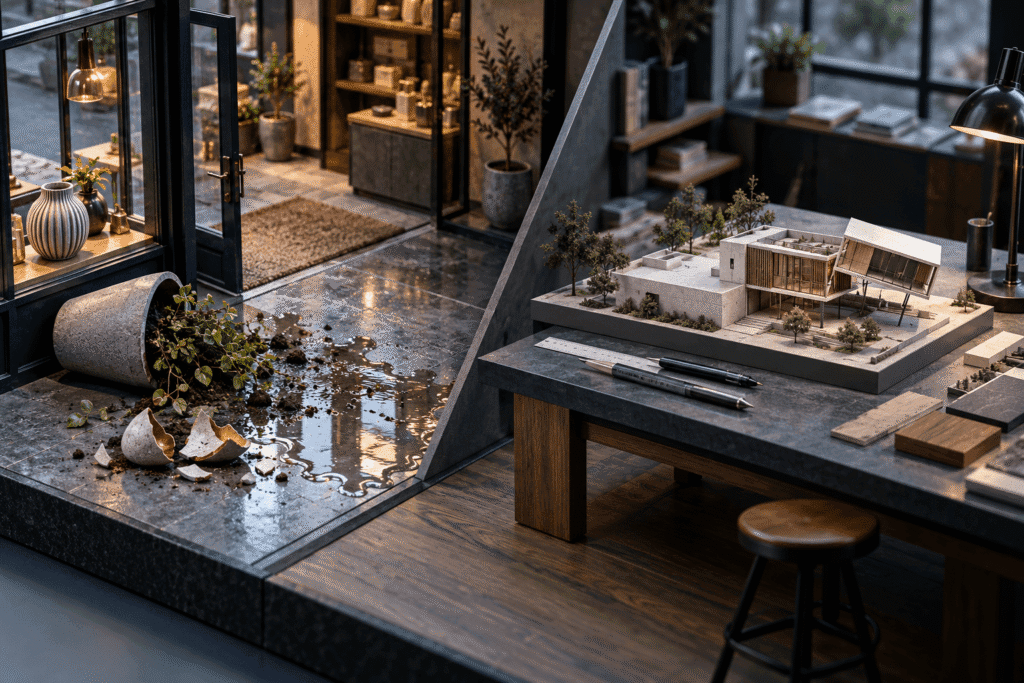
For example, suppose a client visits a consultant’s office and is injured in a fall. That allegation may involve general liability coverage. If the same client later claims that the consultant’s advice caused a financial loss, the allegation may instead involve professional liability coverage.
Although both situations involve the same business and client, they arise from different types of risks.
Policy exclusions also matter. General liability policies may exclude claims arising from professional services, while professional liability policies may exclude bodily injury or property damage except under limited circumstances.
Policy Timing Can Matter
Professional liability policies are often written on a claims-made basis. With this type of policy, coverage may depend on when the professional service occurred, when the claim was first made, and whether the policy was active at the applicable times.
A retroactive date may also limit coverage for services performed before a specified date. If a claims-made policy ends, additional coverage may be needed to address certain claims reported afterward.
General liability policies are commonly written on an occurrence basis, but policy forms vary. Under an occurrence policy, coverage generally depends on whether the covered event happened during the policy period, even if the claim is reported later.
Because these timing provisions can affect coverage, businesses should understand whether a policy is written on a claims-made or occurrence basis before replacing, canceling, or allowing it to lapse.
Which Coverage Does Your Business Need?
The appropriate coverage depends on how your business operates and the claims it could face.
A contractor working at customer properties may have significant exposure to bodily injury or property damage claims. A consultant who provides strategic advice may face greater exposure to allegations involving professional errors or financial losses.
A business that performs physical work and provides professional recommendations may need both types of coverage.
When evaluating your needs, consider:
- The products or services your business provides
- Whether you give professional advice or recommendations
- Where your work is performed
- Whether customers visit your location
- Whether you work with customer property
- Your contracts and client insurance requirements
- The number and responsibilities of your employees
- Your current limits, exclusions, and deductibles
- Whether your professional liability policy is claims-made
Two businesses in the same industry can have different insurance needs. Coverage should reflect the work the business actually performs rather than relying solely on a general industry category.
Common Mistakes to Avoid
Assuming General Liability Covers Every Claim
General liability does not automatically cover every risk connected to a business. Claims involving professional services, employee injuries, business vehicles, cyber incidents, or damage to company property may require different coverage.
Choosing Coverage Based Only on Price
Premium is an important consideration, but it does not show the complete value of a policy. Limits, exclusions, deductibles, endorsements, defense provisions, and coverage triggers can all affect how a policy responds.
Waiting Until a Client Requires Insurance
Some clients and contracts require specific types of coverage or minimum limits. Reviewing insurance requirements before signing an agreement can help a business identify whether its current policies satisfy those terms.
Allowing a Claims-Made Policy to Lapse Without Review
Ending or replacing professional liability coverage without understanding its claims-made provisions could create a gap for claims reported later. Review the policy’s retroactive date and any options for extended reporting coverage before making changes.
Failing to Update Coverage as the Business Changes
Adding employees, services, clients, contracts, or locations can change a business’s risks. Insurance should be reviewed as operations evolve.
Review the Risks Your Business Actually Faces
General liability and professional liability insurance address different types of claims.
General liability generally focuses on certain claims involving bodily injury, property damage, and personal or advertising injury. Professional liability generally focuses on claims alleging errors, omissions, negligence, or other problems with professional services.
Some businesses may need one type of coverage, while others may benefit from both. The appropriate combination depends on the business’s services, operations, contracts, clients, and policy terms.
Warrior Insurance and Services Group helps Colorado businesses compare commercial insurance options based on how they operate and the risks they may encounter. An insurance professional can review your current policies, explain important differences, and help you evaluate available coverage.
